Over latest days, Amazon (NASDAQ: AMZN) inventory hit a brand new all-time excessive. In actual fact, Amazon’s long-term efficiency has been nothing wanting spectacular. Its share value acquire implies that $1 invested in Amazon when it listed in 1997 is now price over $2,800.
Certain, there are nonetheless no dividends. With that form of value acquire, although, I doubt many shareholders are bothered.
In actual fact, they might effectively choose Amazon to maintain doing what it has been doing with its spare money: investing it in additional enterprise development, slightly than utilizing it to fund dividends.
Having not too long ago hit an all-time excessive, it might sound onerous to think about that Amazon inventory is even now a possible discount. However I believe it could be.
The lens issues
That relies upon partly on what strategy one takes to investing.
From a short-term perspective, the price-to-earnings ratio of 36 might not appear low-cost. (Then once more, within the present market, it doesn’t appear outrageously excessive both for a high-growth firm with some large aggressive benefits).
However as an investor, I don’t worry concerning the brief time period when deciding find out how to assemble my portfolio. As a substitute, I take the long-term strategy to investing.
Over the long run, I believe Amazon might but go from energy to energy.
Constructing on its strengths
Amazon has been very revolutionary over a few years. By experimenting with new companies, it has been capable of develop its present aggressive benefit.
It has additionally not been afraid to tug the rug from ventures that it decides are much less promising than hoped. I see that as an indication of assured and decisive administration.
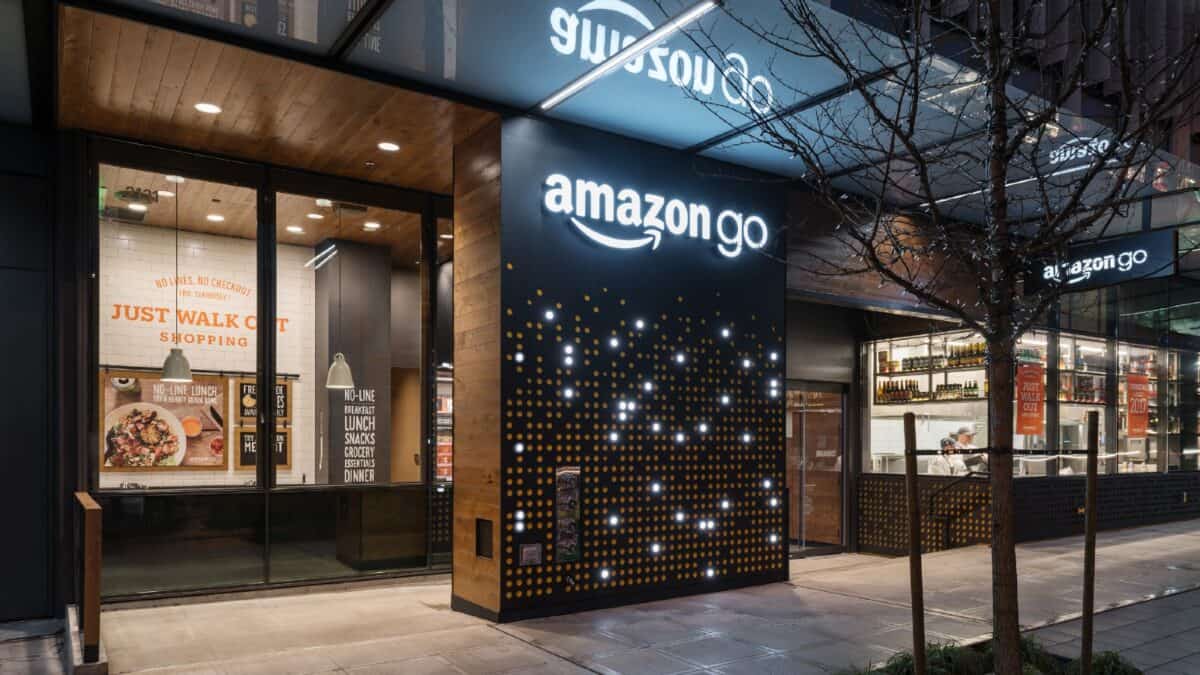
So its on-line retail and market has grown greater and picked up a number of further parts alongside the best way, from bricks-and-mortar outlets to its personal cargo airline.
That alone might imply that the historic heartland of Amazon’s enterprise can develop strongly over the long run. Economies of scale and its robust trade place might assist it develop earnings quicker than revenues.
In the meantime, the larger story from a long-term perspective could also be about AWS (the outdated Amazon Internet Providers).
AI is rocket gas for an already sensible enterprise
Earlier than the AI gold rush, AWS was already a profitable, high-growth enterprise. That has not modified and its server internet hosting enterprise stays large.
However AI demand has taken that to an entire new stage.
How huge?
Put it this manner – within the third quarter, Amazon’s working revenue was $17.4bn. Of that, AWS was chargeable for $11.4bn. That implies that round two-thirds of Amazon’s whole working revenue in its most up-to-date quarter got here from AWS alone.
Pleasure concerning the development potential for AWS explains why the Amazon share value hit an all-time excessive. AWS gross sales had been up by a fifth yr on yr.
Can Amazon’s AI-fuelled development final?
The medium- to long-term demand image for AI-related internet hosting stays unclear. I additionally see a threat opponents might attempt to win market share by competing on value, doubtlessly consuming into AWS’ profitability.
In the meantime, Amazon’s retail enterprise faces ongoing dangers from US tariff uncertainty.
However from a long-term perspective, given its aggressive benefits together with consumer base and confirmed mannequin, I believe Amazon’s present share value might come to be seen as a discount. I see it as a share that traders with a multi-year timeframe ought to think about.
Over latest days, Amazon (NASDAQ: AMZN) inventory hit a brand new all-time excessive. In actual fact, Amazon’s long-term efficiency has been nothing wanting spectacular. Its share value acquire implies that $1 invested in Amazon when it listed in 1997 is now price over $2,800.
Certain, there are nonetheless no dividends. With that form of value acquire, although, I doubt many shareholders are bothered.
In actual fact, they might effectively choose Amazon to maintain doing what it has been doing with its spare money: investing it in additional enterprise development, slightly than utilizing it to fund dividends.
Having not too long ago hit an all-time excessive, it might sound onerous to think about that Amazon inventory is even now a possible discount. However I believe it could be.
The lens issues
That relies upon partly on what strategy one takes to investing.
From a short-term perspective, the price-to-earnings ratio of 36 might not appear low-cost. (Then once more, within the present market, it doesn’t appear outrageously excessive both for a high-growth firm with some large aggressive benefits).
However as an investor, I don’t worry concerning the brief time period when deciding find out how to assemble my portfolio. As a substitute, I take the long-term strategy to investing.
Over the long run, I believe Amazon might but go from energy to energy.
Constructing on its strengths
Amazon has been very revolutionary over a few years. By experimenting with new companies, it has been capable of develop its present aggressive benefit.
It has additionally not been afraid to tug the rug from ventures that it decides are much less promising than hoped. I see that as an indication of assured and decisive administration.
So its on-line retail and market has grown greater and picked up a number of further parts alongside the best way, from bricks-and-mortar outlets to its personal cargo airline.
That alone might imply that the historic heartland of Amazon’s enterprise can develop strongly over the long run. Economies of scale and its robust trade place might assist it develop earnings quicker than revenues.
In the meantime, the larger story from a long-term perspective could also be about AWS (the outdated Amazon Internet Providers).
AI is rocket gas for an already sensible enterprise
Earlier than the AI gold rush, AWS was already a profitable, high-growth enterprise. That has not modified and its server internet hosting enterprise stays large.
However AI demand has taken that to an entire new stage.
How huge?
Put it this manner – within the third quarter, Amazon’s working revenue was $17.4bn. Of that, AWS was chargeable for $11.4bn. That implies that round two-thirds of Amazon’s whole working revenue in its most up-to-date quarter got here from AWS alone.
Pleasure concerning the development potential for AWS explains why the Amazon share value hit an all-time excessive. AWS gross sales had been up by a fifth yr on yr.
Can Amazon’s AI-fuelled development final?
The medium- to long-term demand image for AI-related internet hosting stays unclear. I additionally see a threat opponents might attempt to win market share by competing on value, doubtlessly consuming into AWS’ profitability.
In the meantime, Amazon’s retail enterprise faces ongoing dangers from US tariff uncertainty.
However from a long-term perspective, given its aggressive benefits together with consumer base and confirmed mannequin, I believe Amazon’s present share value might come to be seen as a discount. I see it as a share that traders with a multi-year timeframe ought to think about.