Luxor, a Bitcoin mining derivatives provider, reported a 6–13% annualized Bitcoin financing spread in its September lookback, published Oct. 9. It says lenders and Bitcoin treasury companies bought prepaid mining power and paired it with a price hedge, while miners used the reverse trade to obtain financing.
The return comes from the discount a miner accepts for receiving money upfront. The hedge can fix gross BTC receipts if mining delivery and settlement perform, while the investor’s capital remains exposed to failure in that repayment chain. Luxor’s reported September range does not establish an executed return after costs or a quote available today.
Where the Bitcoin return comes from
Mining power, or hashrate, produces revenue at a rate known as hashprice. Luxor’s contracts express that rate in Bitcoin or dollars per unit of computing power per day. Buying future mining power gives the purchaser exposure to the income that power generates over the contract period.
In a deliverable forward, the buyer pays the full purchase price upfront. The seller must deliver hashrate to Luxor’s Bitcoin Mining Pool, with the buyer’s daily BTC settlement tied to the hashprice index and contracted amount of mining power.
That prepayment supplies financing to the miner. Luxor says deliverable forwards typically trade below comparable non-deliverable forwards to compensate the buyer for credit risk and the cost of committing capital. The lower prepaid purchase price is the source of the lender’s potential profit.
Without a hedge, the buyer’s receipts would vary with the mining-revenue rate. The paired trade adds a sale of a non-deliverable forward, or NDF, which settles in cash rather than requiring physical mining-power delivery.
For the NDF seller, daily settlement is the agreed hashprice minus that day’s index rate, multiplied by the contracted hashrate. When the index is below the agreed price, the seller receives the difference. When it is above, the seller owes the difference.
If the two legs use the same BTC denomination, hashrate quantity, settlement dates and index methodology, their price exposures cancel. Fully delivered mining receipts at the daily index rate, plus the NDF settlement, equal receipts at the fixed NDF rate. The profit depends on how much those receipts exceed the prepaid purchase cost and other costs.
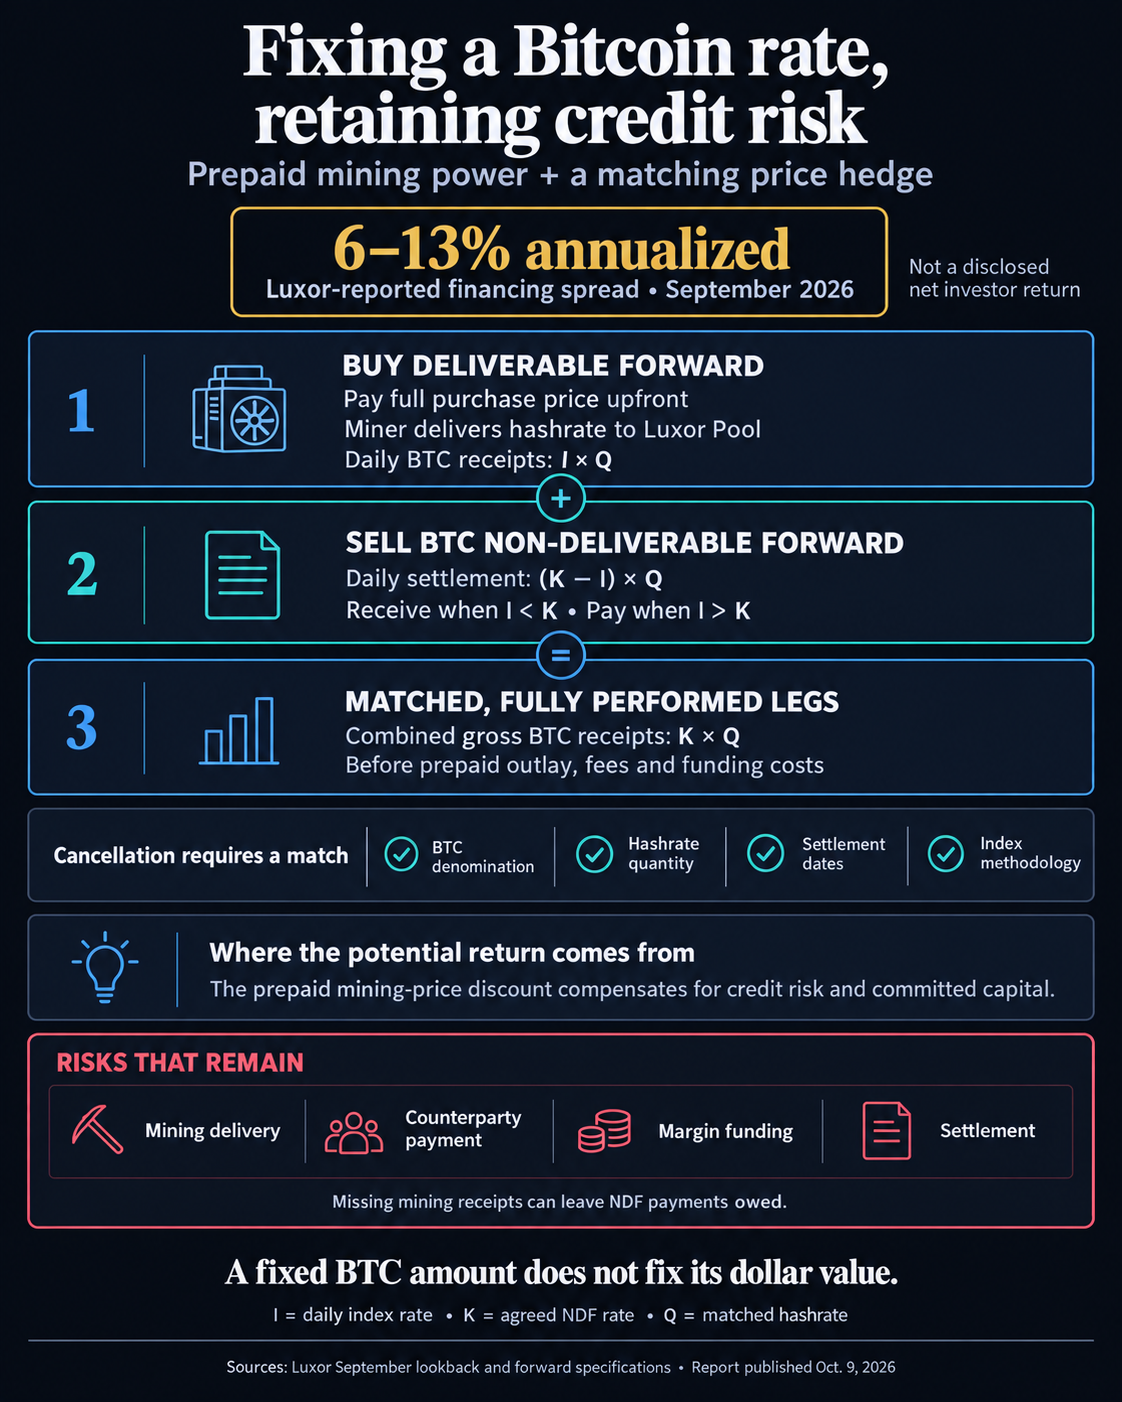
The matching conditions matter. A hedge covering different quantities or dates leaves part of the mining revenue exposed. A dollar-denominated contract also cannot simply be substituted for a BTC-denominated one while preserving the same Bitcoin payoff.
A BTC-denominated hedge also leaves the dollar value of Bitcoin receipts exposed to BTC/USD changes.
Luxor’s product pages describe monthly contracts up to 18 months out and custom durations. That is the general product range; the September financing discussion does not identify which tenors produced the reported 6–13%, or give its annualization formula.
Annualized pricing also does not mean an investor earns the quoted percentage over any shorter contract. The actual contract period, repayment timing, costs and capital committed across both legs determine the return on the investor’s funds.
Delivery failure can leave the hedge running
The cancellation works because the buyer receives the mining revenue against which the NDF settles. If promised mining power is not delivered and the shortfall is not cured, that revenue leg can be smaller than expected while the hedge still has settlement obligations.
When settlement hashprice exceeds the NDF’s fixed rate, the seller owes the difference, expecting higher mining receipts to offset it. If those receipts fail to arrive, the price hedge can require payment without the corresponding income.
There is also a distinction between the miner supplying the output and the investor’s contractual counterparty. Luxor’s order-book documentation says Luxor is counterparty to both the buyer and seller. The platform displays buy and sell orders, and its derivatives team contacts the parties to confirm trades; the book itself is not an execution system.
For an investor, that makes Luxor’s own performance part of the repayment chain alongside the mining operation.
Luxor’s upfront-payment procedures require seller credit profiling before money is advanced. The requirements cover mining-site and power documents, insurance, pool performance, financial statements and future obligations. Its margin policy also lists documentation for a performance bond or guarantor among its supplemental checks.
Credit checks reduce uncertainty about a seller’s ability to perform, while recovery after failure depends on enforceable claims. The public requirements do not specify a complete repayment priority or identify which assets an investor could enforce against after default.
For eligible investors, collateral custody and the ability to exit remain part of the credit exposure. The order book allows open orders to be canceled; that does not establish an exit from a confirmed forward.
Margin changes the capital calculation
Collateral determines how much additional capital may be needed to maintain the hedge. Luxor’s margin policy requires BTC collateral for BTC contracts and collects variation margin when the lower of realized and unrealized margin balances falls below maintenance requirements. Credit-qualified deliverable sellers can have custom procedures based on realized balances.
The policy describes initial margin as protection against potential exposure during the time needed to close out and replace a defaulted position.
The public schedules are not consistent: the NDF page quotes 18% BTC initial margin and the DF page quotes 18% seller hashprice margin plus possible delivery margin, while the general policy lists 17.5% BTC initial and 14% maintenance on non-offset future daily notional. The pages do not explain the difference.
The policy identifies Nov. 14, 2025, as its last initial-margin evaluation. Qualified BTC deliverable sellers can receive discretionary initial terms after supplemental credit profiling, so neither product-page rate establishes a universal requirement for the paired trade.
Prepaid DF buyers are exempt from that leg’s initial-margin schedule because they already pay in full. That exemption does not establish that their NDF leg is collateral-free.
That capital matters when comparing the reported spread with an investor’s net return. Fees, execution prices and any additional funds committed to support the hedge can affect the amount earned relative to the money put at risk.
Luxor’s Steelhead Capital Management case study describes the pairing in practice: Steelhead bought physical hashrate upfront, added an NDF to fix hashprice, and used Luxor Pool for delivery, reward distribution and settlement.
Luxor says daily repayment reduces exposure over the contract’s life. That supports the mechanism of returning funds progressively, while the remaining unpaid amount still depends on performance.
Access is also restricted. Luxor’s resources page says participants must qualify as Eligible Contract Participants. Its examples include entities with more than $10 million in assets and entities with at least $1 million in net worth hedging commercial risk. The structure is not universally available to retail Bitcoin holders.