Picture supply: Sam Robson, The Motley Idiot UK
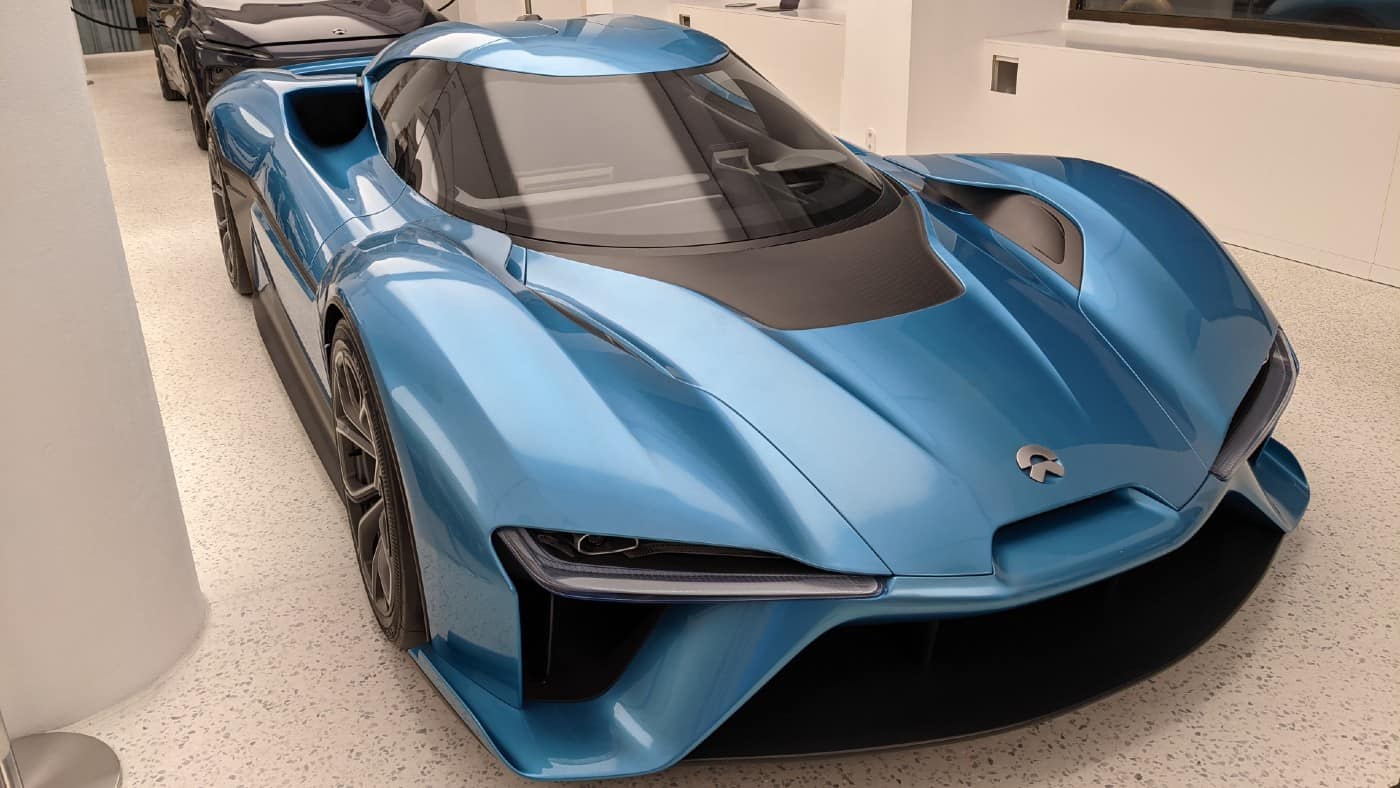
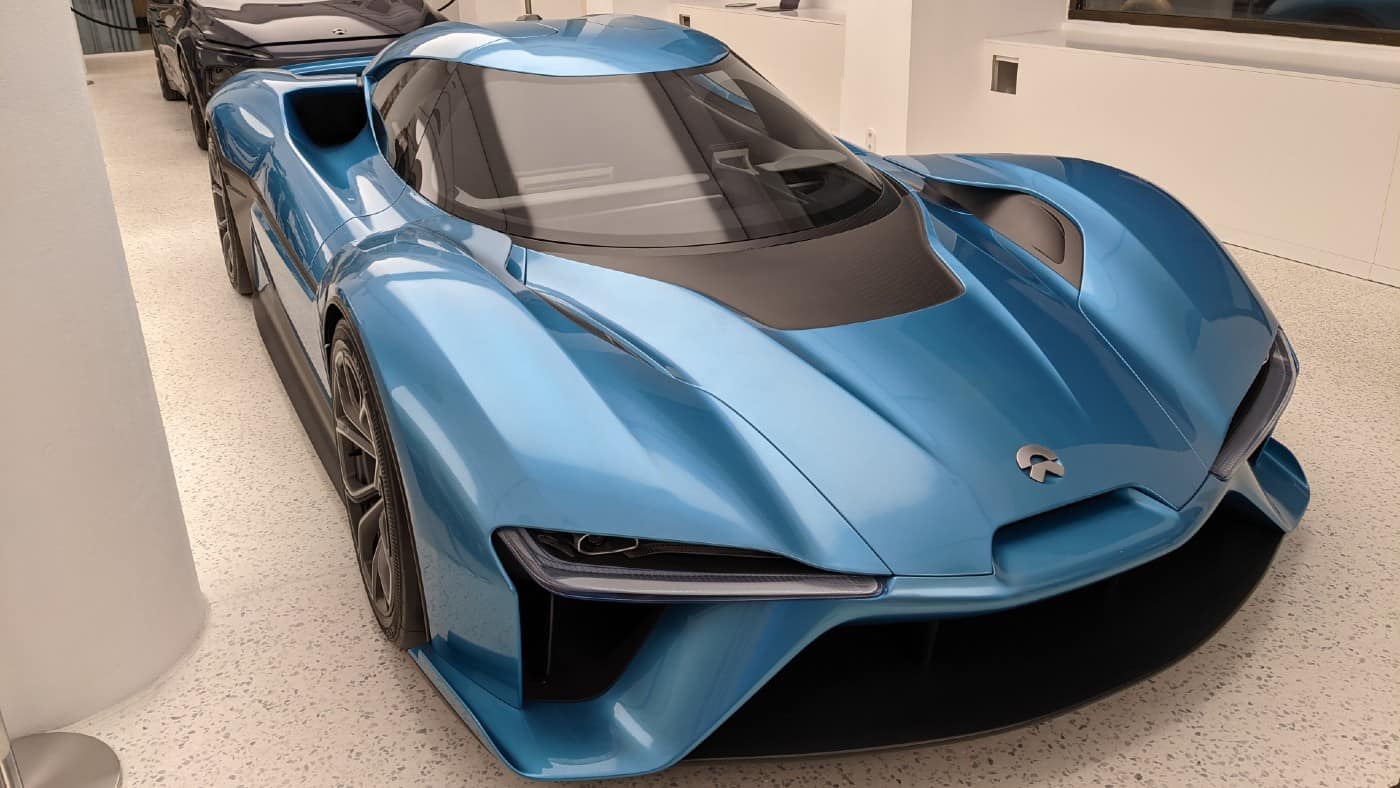
Tesla, it’s honest to say, has had a tough 2025 thus far. The inventory value is up 443% over the previous 5 years, however has tumbled 36% because the begin of 2025. Against this, electrical car rival NIO (NYSE: NIO) is up 1% thus far this yr. 1% is hardly the stuff of investor desires – however it’s a lot higher than business big Tesla has managed. So, may now be the time so as to add NIO inventory to my portfolio?
A difficult market
For now, I believe the reply isn’t any.
Tesla’s challenges, because the model reels from its chief government’s excessive political profile, are partly self-inflicted. However solely partly.
The truth is that the electrical car market has moved on considerably from the place it was even only a few years in the past.
Demand is greater. However there are additionally a number of credible electrical car firms promoting vehicles. That has had an influence on costs as these makers attempt to compete. In flip, revenue margins have taken successful throughout the business.
So from NIO’s perspective, there’s each good and unhealthy information.
The excellent news is that the electrical car market is in progress mode. The unhealthy information is that that has come on the value of decrease revenue margins, one thing which basically tends to learn massive companies which have better economies of scale.
As I see it, although, NIO has one other particular problem: advances in battery know-how.
Dramatically quicker claimed battery charging instances might be a boon for rivals like BYD (and its long-term investor Warren Buffett) and Tesla. However they threaten to make NIO’s battery swapping know-how largely out of date. Thus far, that had been a key aggressive benefit.
Nonetheless some causes for hope
Nonetheless, NIO inventory has carried out markedly higher than Tesla inventory thus far this yr. So may my considerations be overdone?
Whereas Tesla inventory has crashed in 2025, BYD is up a storming 54%. Positive, NIO inventory shouldn’t be performing as poorly as its US rival – however its 2025 share value progress has lagged far behind that of its native Chinese language competitor.
In the meantime, within the first quarter, BYD’s income grew 36% yr on yr to round £17.6bn. Examine that to NIO. It has not but launched first-quarter numbers, however within the fourth quarter, revenues have been round £2.0bn, a 15% year-on-year progress.
Winners pulling forward
That’s not an apples-to-apples comparability, as the primary quarter of this yr noticed important geopolitical threat escalation.
However clearly, NIO is much behind each BYD and Tesla by way of absolute gross sales revenues. Nonetheless, these revenues are substantial – and progress charges might lag BYD badly, however are far forward of Tesla at the moment.
Nonetheless, a key aggressive benefit NIO has invested closely in is now below risk. In the meantime, it lacks the large scale of BYD and Tesla because the market consolidates.
By itself, that doesn’t essentially put me off shopping for NIO inventory, although I believe the funding case has weakened given what I discussed above.
What does put me off, nonetheless, is that whereas BYD and even Tesla stay firmly worthwhile, NIO stays firmly loss-making.
A weaker Tesla share value doesn’t essentially assist NIO. NIO must be judged by itself deserves. Till it has confirmed it could actually generate profits, I can’t be investing.